Platinum Tree Financial
  • SERVICES
    • BUSINESS OWNERS
      • FINANCIAL ADVICE
      • RISK MANAGEMENT PLANNING
      • INSURANCE PLANNING
      • SUCCESSION PLANNING
      • EMPLOYEE BENEFITS
        • HEALTH BENEFITS
        • RETIREMENT BENEFITS
        • HEALTH SPENDING ACCOUNT
    • INCORPORATED PROFESSIONALS
      • FINANCIAL ADVICE
      • HEALTH SPENDING ACCOUNT
    • INDIVIDUALS & FAMILIES
      • FINANCIAL ADVICE
      • RISK MANAGEMENT PLANNING FOR YOUNG FAMILIES
      • RISK MANAGEMENT PLANNING FOR RETIREES & MATURE FAMILIES
      • INSURANCE PLANNING
    • INSURANCE
      • INSURANCE PLANNING FOR FAMILIES
      • INSURANCE PLANNING FOR BUSINESS OWNERS
      • DISABILITY
      • CRITICAL ILLNESS
      • LIFE
        • PERSONAL
        • CORPORATE
      • HEALTH INSURANCE
      • LONG TERM CARE INSURANCE
      • TRAVEL INSURANCE
      • CREDITOR INSURANCE
    • RISK MANAGEMENT
      • YOUNG FAMILIES
      • RETIREES AND MATURE FAMILIES
      • BUSINESS OWNERS
    • TAX DRIVEN STRATEGIES
      • INSURED RETIREMENT PROGRAM
      • SHARED OWNERSHIP CRITICAL ILLNESS
      • IMMEDIATE FINANCING ARRANGEMENT
      • CORPORATE ESTATE BOND
  • ABOUT
    • ABOUT
    • SUPPLIERS
    • PRIVACY & WEBSITE TERMS OF USE
  • NEWS
  • CONTACT
  • Menu Menu

Archive for category: Insurance

Empowering Your Family’s Financial Future: A Comprehensive Guide to Budgeting

September 1, 2026/in Blog, Debt, disability, disability insurance, Family, financial advice, Financial Planning, individuals, Insurance, rdsp/by Platinum Tree Financial

Taking charge of your family’s financial well-being through effective budgeting is a crucial step in securing a brighter future. We’ll explore the significance of budgeting and provide practical tips to help you manage your money wisely while ensuring the best possible support for your loved ones, including those with disabilities and their Registered Disability Savings Plan (RDSP).

Why Budgeting Matters for Families

Budgeting is a powerful financial tool that holds importance for all families:

  1. Financial Clarity: It offers a clear overview of your family’s income and expenses, helping you make informed decisions about allocating funds.

  2. Goal Achievement: Budgeting helps you allocate funds not only for your loved one’s RDSP but also for other family financial goals, such as saving for education or a home.

  3. Expense Control: It identifies areas where you can cut back on expenses, freeing up money for your family’s financial priorities.

  4. Debt Reduction: By tracking spending, you can allocate extra funds to pay down debt faster, ensuring your family’s financial stability.

  5. Emergency Preparedness: A budget provides a financial safety net for unexpected expenses, which can be especially critical for families with additional financial responsibilities.

Steps to Effective Budgeting for Families

  1. Calculate Income: Determine your total monthly income, including salaries, government benefits, and any disability-related support for your loved one.

  2. List Expenses: Categorize expenses into fixed (e.g., housing, utilities) and variable (e.g., groceries, entertainment).

  3. Set Financial Goals: Define short-term and long-term financial goals for your family, ensuring that your loved one’s RDSP contributions are part of the plan.

  4. Create a Budget: Use budgeting tools or apps to allocate income to expenses, savings, and financial goals without exceeding your income.

  5. Monitor and Adjust: Regularly track spending against your budget, making necessary adjustments to ensure your family’s financial health.

Tips for Successful Budgeting

  1. Be Realistic: Set achievable goals and create a budget that accommodates your family’s unique needs, including the financial responsibilities associated with the RDSP.

  2. Prioritize Savings: Ensure that contributing to your loved one’s RDSP is a top financial priority, but don’t forget to save for other family goals too.

  3. Emergency Fund: Maintain an emergency fund to cover unexpected expenses, which can benefit all family members.

  4. Review and Cut Expenses: Periodically review expenses to find areas where you can save and allocate more funds to your family’s financial priorities.

  5. Pay Yourself First: Treat savings, including RDSP contributions, as non-negotiable expenses, just like other essential bills.

  6. Seek Professional Advice: Consult a financial advisor who specializes in disability-related financial planning for tailored guidance.

Budgeting is your family’s pathway to financial security and ensuring a brighter financial future. By budgeting wisely and prioritizing your loved one’s financial well-being, you can control your family’s finances, reduce stress, and work towards a future filled with financial peace of mind. Remember, financial success for families means making informed choices that align with your values and aspirations. Start budgeting today to achieve financial wellness for your entire family, balancing the needs of all family members, including those who rely on the support of the RDSP.

https://platinumtreefinancial.ca/wp-content/uploads/2026/09/Add-a-heading.jpg 300 500 Platinum Tree Financial https://platinumtreefinancial.ca/wp-content/uploads/2020/03/platinumTreeEnfold.jpg Platinum Tree Financial2026-09-01 11:25:502026-09-01 11:26:04Empowering Your Family’s Financial Future: A Comprehensive Guide to Budgeting

You Just Inherited Money: What to Do First

August 3, 2026/in Blog, Insurance, Investment/by Platinum Tree Financial

You Just Inherited Money: What to Do First

Coming into an inheritance is a strange mix of feelings. There is often grief, because the money usually comes after losing someone you care about. There can also be relief, pressure, or even guilt. On top of all that, you may feel a quiet panic about doing the right thing with the money.

Here is the good news. You have more time than you think. The smartest first move is almost never a big move. Let us walk through what to do first, one calm step at a time.

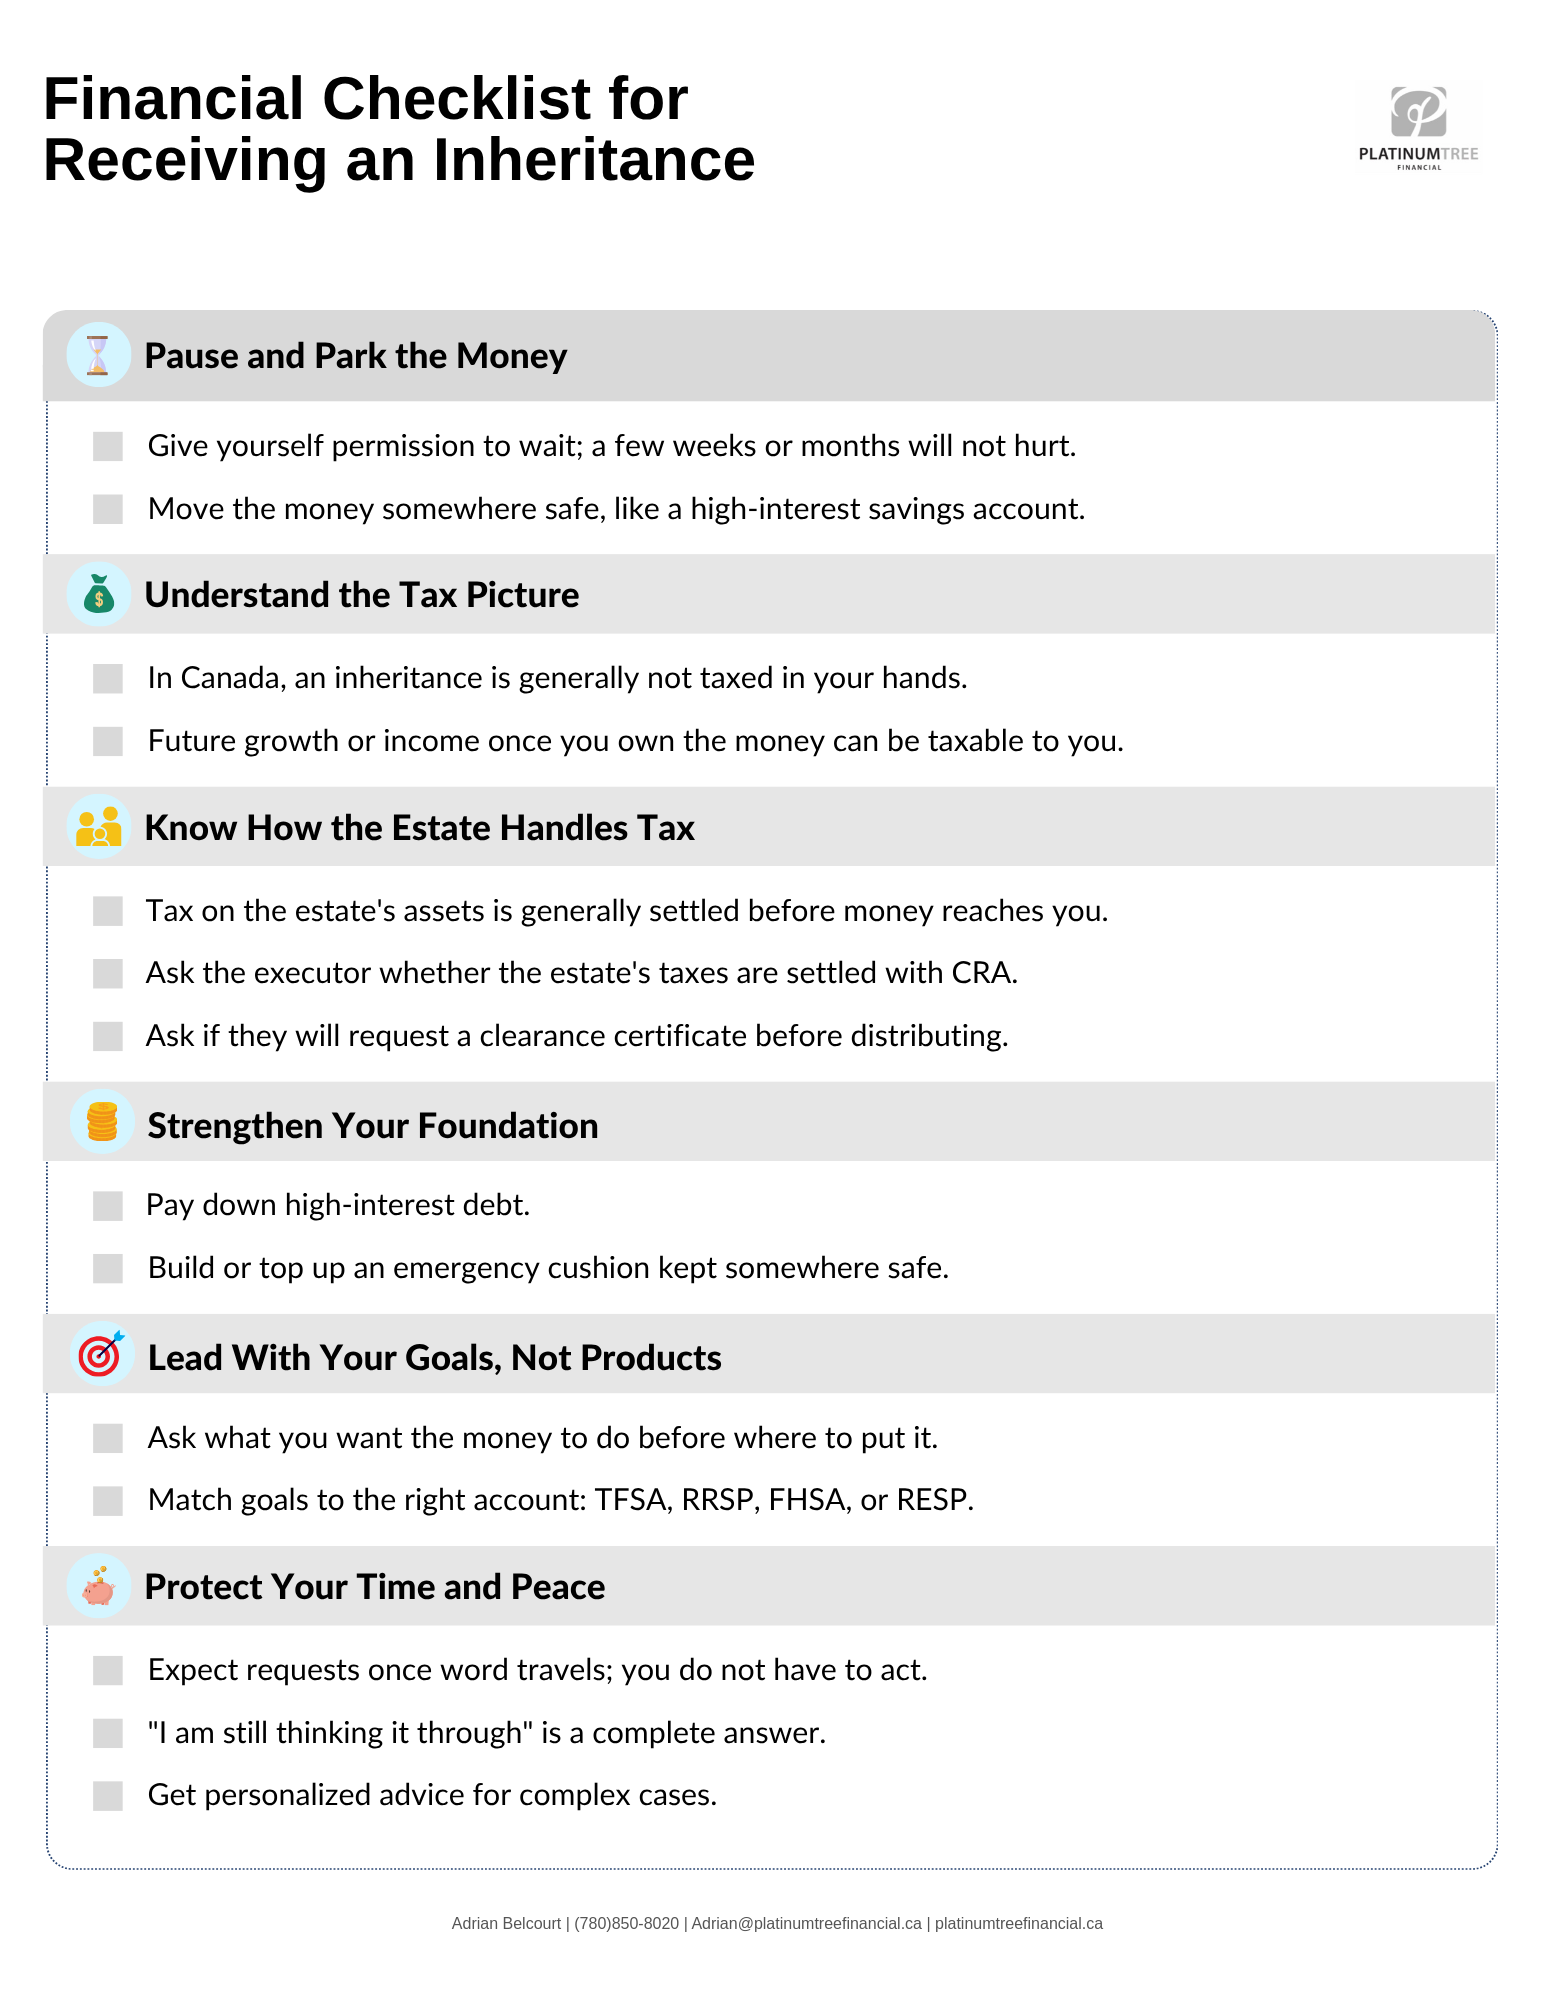
First, Pause and Park the Money

There is no rush. Money that has been waiting in an estate is not going anywhere, and a few weeks or months of thinking time will not hurt you. In fact, that pause can save you from choices you might regret.

When a large sum lands in your account, it can feel like you should do something with it right away. Resist that pull. Big decisions made in the early days of grief or excitement are often the ones people wish they could undo.

For now, put the money somewhere safe and boring. A high-interest savings account is a good home. Your money stays easy to reach, it is protected, and it earns a bit while you think. There is no need to invest it, lend it, or spend it until you have had time to plan with a clear head.

Understand the Tax Picture

This part surprises a lot of people, in a good way. In Canada, an inheritance is generally not taxed in the hands of the person who receives it. You usually do not report the money you inherit as income, and you do not pay tax just for receiving it.

Why is that? Because the tax is generally settled by the estate before the money reaches you. When someone passes away, their final tax return is prepared, and any tax owing on their assets is handled at that stage. The money is usually distributed to family and other heirs after that step. So by the time it gets to you, the tax piece has generally already been dealt with.

This does not mean money you inherit is tax-free forever. Once you own it, any future growth, interest, or income it earns can be taxable to you, just like your other money. But the act of inheriting it, on its own, generally does not create a tax bill for you.

brandableContent

How Assets Are Treated in the Estate

For most people receiving an inheritance, the reassuring part is that this tax work happens at the estate level, not yours. You usually do not pay tax just for receiving an inheritance. If you would like to understand what happens behind the scenes, here is what happens to different assets before they reach you. The rules depend on the type of asset.

For non-registered assets, such as an investment account or a property that is not a primary home, assets are generally deemed disposed at fair market value on death, and accrued gains are reported on the final return unless a spousal rollover applies. The rollover works like this: these assets can roll to a spouse or common-law partner, or a qualifying spousal trust, on a tax-deferred basis. Otherwise, the accrued gain is reported on the final return.

For an RRSP or RRIF, the full value is generally treated as received and added to income on the final return, except where a spouse or common-law partner is a successor annuitant or receives an eligible rollover, or where a financially dependent child or grandchild qualifies for a rollover.

For a TFSA, growth inside a TFSA is tax-free to the date of death. A spouse or common-law partner named as successor holder can continue it tax-free, where that option is available. A named beneficiary follows set steps, and later growth can be taxable.

One simple thing is worth doing as a beneficiary: it is fair to ask the executor whether the estate’s taxes are settled, and whether they have requested a clearance certificate, before the estate is fully wound up. A clearance certificate is CRA’s confirmation that the estate’s taxes are paid, and it is something the executor may want to request before distributing the estate.

Pay Down Debt and Shore Up Savings

Once you have paused and you understand the tax basics, you can start to think about using the money well. Two steps tend to give the best return for the least worry.

The first is paying down high-interest debt. Credit card balances and other costly loans can quietly drain your budget every month. Clearing them is like giving yourself a guaranteed return, because you stop paying that interest for good. Few investments can promise that.

The second is building or topping up an emergency cushion. This is simply cash set aside for surprises, kept somewhere safe and easy to reach, like that high-interest savings account. A solid cushion means the next car repair or job hiccup does not throw your life off track. Together, clearing costly debt and holding a cash buffer give you a calm, steady base before you do anything fancier.

Think About Goals Before Products

It is tempting to jump straight to “where should I put this money?” A better question is “what do I want this money to do for me?” Goals come first. Products come second.

Maybe you want to retire a little sooner, buy a first home, save for a child’s schooling, or just feel more secure. Once your goals are clear, registered accounts can help you reach them, and each one has a job:

  • A TFSA lets your savings grow tax-free, and you can take money out for any purpose.
  • An RRSP is built for retirement and can lower your taxable income in the year you contribute.
  • An FHSA is designed to help you save toward a first home.
  • An RESP helps you save for a child’s education after high school, with government grants that add to what you put in.

Each account has its own contribution room and rules, and these change over time. You can check your available room and the current limits through CRA My Account or at canada.ca. Matching the right account to the right goal is what turns a windfall into lasting progress.

If your situation involves cross-border elements, such as inheriting foreign property, or executors or beneficiaries in different countries, the tax picture can be more complex and may involve foreign reporting or foreign estate taxes. That is one of the times when personalized advice is well worth it.

Watch for Pressure and Take Your Time

A sudden sum of money can change how people treat you, and how you feel. Word travels. You may get requests for loans, gifts, or “can’t-miss” opportunities. You may also feel pressure inside your own family about what the money should be used for.

None of that means you must act. It is your inheritance, and you are allowed to take your time. A simple, kind answer works well: “I am still thinking it through.” That one sentence buys you space and protects you from rushed choices.

Coming into money you did not plan for is a lot to hold, especially when it follows a loss. So go gently. Park it somewhere safe, remember that your inheritance is generally not taxed to you when you receive it, and let your goals lead the way. The single best first step is often the simplest one: give yourself permission to pause. What would feeling truly settled with this money look like for you?

This content is provided for general informational purposes only. It is not intended to provide investment, tax, or legal advice, and should not be relied upon as such.

Sources:

  • Doing taxes for someone who died
  • If a TFSA holder dies

https://platinumtreefinancial.ca/wp-content/uploads/2026/08/You-Just-Inherited-Money-A-Calm-First-Steps-Checklist.png 700 1200 Platinum Tree Financial https://platinumtreefinancial.ca/wp-content/uploads/2020/03/platinumTreeEnfold.jpg Platinum Tree Financial2026-08-03 13:07:412026-08-03 13:08:07You Just Inherited Money: What to Do First

What Is Participating Whole Life Insurance?

June 1, 2026/in 2026, Blog, Insurance/by Platinum Tree Financial

What Is Participating Whole Life Insurance?

Most people buy life insurance for one reason: to make sure their family is protected if something happens to them. But there is a type of life insurance that does something more – it builds value over time while you are still alive. That type is called participating whole life insurance, and it works very differently from the term policies most Canadians are familiar with.

Here is what it means, how it works, and whether it might be a fit for you.

Permanent Coverage That Does Not Expire

Term life insurance covers you for a set period – 10, 20, or 30 years. Participating whole life insurance is permanent. It covers you for your entire life, as long as premiums are paid, and the death benefit is guaranteed.

That permanence is the first major difference. But the bigger difference is what happens to your premiums while you are alive.

With a term policy, your premiums go entirely toward the cost of insurance. With participating whole life, the insurer pools premiums into a participating account that is professionally managed. Dividends may be paid when the account’s experience is favourable, based on factors such as investment returns, expenses, and mortality experience.

How Dividends Work

The word “dividend” here is different from stock dividends. In the context of a participating whole life policy, a dividend is a share of the insurance company’s surplus – essentially, the company returning a portion of the money when investment performance, claims experience, and expenses go better than expected.

These dividends are not guaranteed. They are declared each year by the insurance company based on how the participating account performed. That said, many Canadian participating insurers have long histories of paying dividends, though past performance does not guarantee future results.

When you receive a dividend, you have a few options for how to use it:

  • Take it as cash. The dividend is paid to you directly.

  • Apply it to your premium. It reduces how much you pay out of pocket.

  • Buy additional paid-up insurance. This is the most common choice. The dividend purchases more coverage, which in turn earns its own dividends. Over time, this compounds.

  • Leave it on deposit. The dividend sits with the insurer and earns interest.

Most policyholders who hold participating whole life for the long term choose to purchase additional paid-up insurance, because it accelerates both the death benefit and the cash value of the policy.

The Cash Value

One of the most distinctive features of a participating whole life policy is that it builds cash value. The policy builds guaranteed cash value as part of its structure, and dividends can add a non-guaranteed layer of growth if they are used to buy paid-up additions.

The policy accumulates cash value that you may be able to access, subject to policy terms, in a few ways:

  • Policy loans. You can borrow against the cash value without going through a lender or credit check. Policy loans do not have fixed repayment schedules, but any unpaid balance can reduce the death benefit.

  • Surrendering the policy. If you decide you no longer need the coverage, you can cancel the policy and receive the accumulated surrender value. The tax treatment on surrender can be technical and depends on the policy’s adjusted cost basis — the disclaimer at the end of this article applies here.

The cash value grows on a guaranteed basis, separate from the dividends. The dividends, if used to purchase paid-up additions, add a non-guaranteed layer of growth on top.

Who Is This Type of Policy For?

Participating whole life is not the right fit for every situation. Because premiums are higher than term insurance, it is most commonly used by people who have a long-term need for life insurance and who can sustain the premium over time.

Some of the most common situations where it makes sense:

Families building long-term wealth. For parents who want to ensure a guaranteed death benefit no matter when they pass, plus build a tax-advantaged asset over decades, participating whole life offers both.

Business owners and incorporated professionals. A participating whole life policy held inside a corporation may offer a tax-efficient approach to building cash value inside a permanent policy, depending on the structure and the corporation’s specific situation. It can be used by incorporated professionals – such as dentists and physicians – to redirect excess corporate cash into a long-term, protected asset.

Estate planning. For those who want to leave a specific, guaranteed sum to their heirs or a charitable organization, a participating whole life policy creates a known outcome – the death benefit- regardless of when death occurs.

High net worth individuals. When other registered accounts (TFSA, RRSP) are maximized, participating whole life can offer a tax-efficient way to build cash value inside a permanent policy, outside of registered limits.

How It Fits Alongside Term Insurance

Term and participating whole life insurance are not competitors- they serve different purposes, and many Canadians use both at different stages of life.

Term insurance is a straightforward, affordable way to protect your family during the years it matters most – while a mortgage is being paid down, while children are young, or while income replacement is the primary concern. It does exactly what it is designed to do.


Participating whole life steps in when the need for coverage is permanent, when building long-term cash value matters, or when the policy is part of a broader estate or corporate strategy. The two products often complement each other well, and choosing one does not mean ruling out the other.

What to Take Away

Participating whole life insurance combines permanent death benefit protection with a growing cash value and the potential for dividends. It is a longer-term commitment with higher premiums, and it is designed for situations where permanence, cash value, and legacy planning are part of the picture.

If you are considering permanent life insurance, take time to review how dividend performance has held up at the insurer you are looking at, understand the various dividend options, and think through whether the long-term commitment fits your situation.

This content is provided for general informational purposes only. It is not intended to provide investment, tax, or legal advice, and should not be relied upon as such. Policy design, dividend scale performance, cash value growth, and tax treatment vary by insurer and by the specific policy contract. Always review the policy illustration and contract terms carefully.

Sources:

Participating Life Insurance – CLHIA

https://platinumtreefinancial.ca/wp-content/uploads/2026/06/WhatisWholLifeFI.png 700 1200 Platinum Tree Financial https://platinumtreefinancial.ca/wp-content/uploads/2020/03/platinumTreeEnfold.jpg Platinum Tree Financial2026-06-01 12:19:072026-06-01 12:19:32What Is Participating Whole Life Insurance?

Corporate Life Insurance Planning

August 1, 2025/in Blog, business owners, Insurance, life insurance, Professional Corporations/by Platinum Tree Financial

Corporate Life Insurance Planning: Protect, Reward, and Plan for the Future

Running a business in often means wearing multiple hats—owner, leader, and long-term planner. But have you ever thought about what happens if you or a key person in your company passes away unexpectedly? Or how you might use your corporation to support retirement, reward top talent, or prepare for taxes when transitioning ownership?

Corporate life insurance is one of the most flexible and underused tools available to business owners. It helps protect your company, reduce taxes, and build lasting value—both during your working years and when it’s time to pass the business on.

Let’s look at how business owners are using corporate-owned life insurance to protect their companies and their families while preparing for the future.

brandableContent

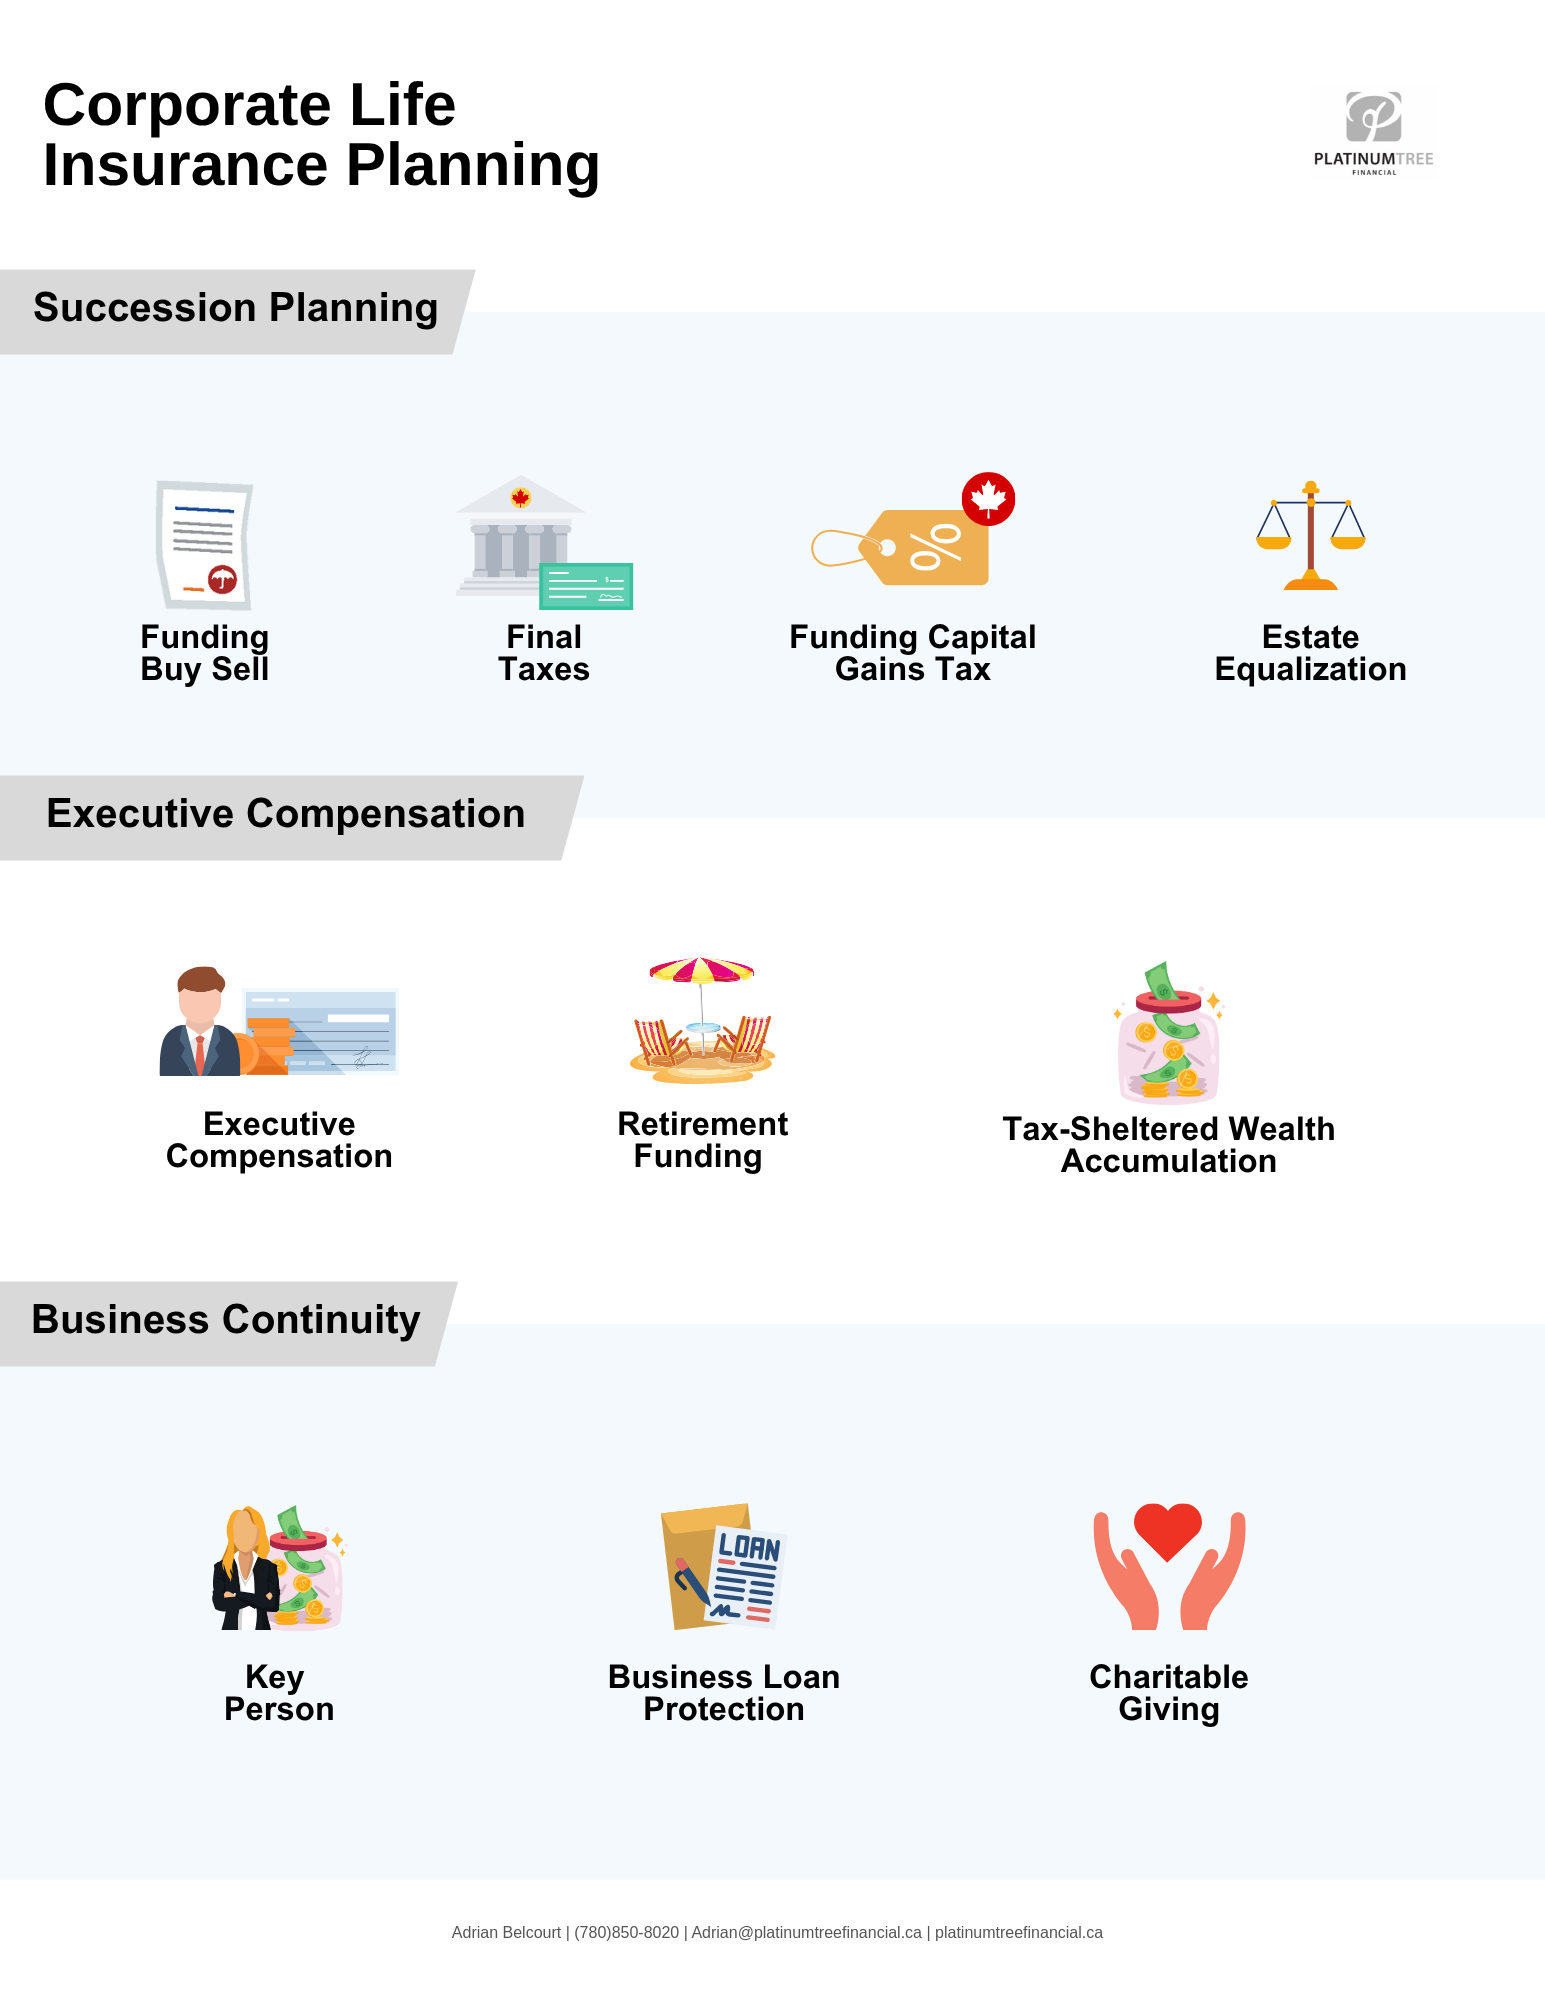
Succession Planning: Make Transitions Smooth and Tax-Smart

For many business owners, their company is one of their largest assets. But passing it on—whether to family or a partner—comes with major financial challenges. Life insurance can help.

Funding a Buy-Sell Agreement

If you have a business partner, a buy-sell agreement ensures that if one of you passes away, the other can buy the shares from the deceased’s estate. The problem? That buyout requires cash—often hundreds of thousands, if not millions. Life insurance is a cost-effective way to fund that agreement, so ownership stays in the right hands without putting a strain on the business or the family.

Covering Final Taxes and Capital Gains

When a business owner dies, the Canada Revenue Agency treats it as if they sold their shares—even if they didn’t. This “deemed disposition” creates a tax bill that can surprise even the most prepared families. Life insurance provides a tax-free lump sum that the corporation can use to cover this cost, helping preserve the value of the business and avoid selling off assets under pressure.

Estate Equalization

If you plan to leave the business to one child but want to treat your other children fairly, life insurance can help. The business goes to the child who’s involved, while other beneficiaries receive the life insurance proceeds. It’s a clean, tax-efficient way to avoid family conflict and keep the business whole.

Executive Compensation: Attract and Retain Top Talent

In a competitive hiring environment, offering the right benefits can make all the difference. Life insurance isn’t just about protection—it can be a powerful way to reward and retain your most valuable people.

Executive Compensation Strategies

Life insurance can be part of a compensation package that rewards top performers, especially those who are key to the company’s success. Whether structured as a bonus plan or part of a long-term incentive, this can be a powerful way to align goals and build loyalty.

Retirement Funding

Permanent life insurance policies (like whole life or universal life) build cash value over time. That value grows tax-deferred and can be accessed through policy loans or collateralized lending. Business owners and executives often use this as an additional retirement income stream, especially if they’ve already maxed out RRSP or TFSA contributions.

Tax-Sheltered Wealth Accumulation

The cash value inside a permanent life insurance policy grows on a tax-deferred basis. When a corporation owns the policy, this growth can be especially strategic. It allows the business to use surplus cash to build value in a tax-efficient way, diversify beyond traditional investments, and potentially access funds later with fewer tax consequences. This approach is particularly useful for businesses with retained earnings that would otherwise be subject to higher corporate tax rates.

Business Continuity: Protect What You’ve Built

An unexpected death can do more than cause emotional pain—it can disrupt operations, shake client confidence, and even put the business at risk. Insurance helps ensure your company can keep going.

Key Person Protection

If you or someone else is essential to the day-to-day success of your business, losing that person could be a major financial blow. A life insurance policy on that individual can help the business recover, cover short-term losses, and fund the search for a replacement.

Business Loan Protection

Many lenders require insurance on owners or key executives as a condition of financing. If that person passes away, life insurance ensures the loan is paid off, protecting both the lender and the company’s assets. It can also unlock better lending terms and help avoid personal guarantees.

Charitable Giving Through the Corporation

For business owners looking to give back, corporate life insurance can also be used to support charitable causes. The business can own a policy and name a charity as the beneficiary—creating a lasting impact while offering potential tax benefits.

Bringing It All Together

Corporate life insurance isn’t just about “what if”—it’s about building a stronger, more resilient business and unlocking smart ways to manage wealth inside your company. Whether you’re focused on succession, rewarding your team, or protecting operations, insurance can help you take action today that pays off for years to come.

If you haven’t reviewed your corporate insurance strategy recently, now’s a great time to take a fresh look.

Disclaimer: This article is for informational purposes only and does not constitute financial, legal, or tax advice. Always consult a qualified professional regarding your specific situation. We are not responsible for any actions taken based on this content.

https://platinumtreefinancial.ca/wp-content/uploads/2025/08/Corporate-Life-Insurance-Planning-FI.png 700 1200 Platinum Tree Financial https://platinumtreefinancial.ca/wp-content/uploads/2020/03/platinumTreeEnfold.jpg Platinum Tree Financial2025-08-01 06:00:532025-08-01 06:01:32Corporate Life Insurance Planning

Embracing a Work Optional Lifestyle in Retirement

October 1, 2024/in Blog, Estate Planning, Family, financial advice, Financial Planning, individuals, Insurance, Investment, life insurance, Retirees, retirement/by Platinum Tree Financial

Retirement is a significant milestone in your life, symbolizing the culmination of years of hard work and financial planning. However, in recent years, there has been a shift in the way people perceive retirement. Many retirees are no longer looking to retire solely for relaxation but are seeking a more dynamic and fulfilling work-optional lifestyle. As financial advisors, we believe it’s essential to educate our prospects about this exciting trend and how they can achieve it.

What is a Work Optional Lifestyle?

A work-optional lifestyle in retirement is all about having the financial freedom and flexibility to choose whether or not to work, without compromising your financial security. It’s about shifting from the traditional retirement model, where you simply stop working, to a more modern approach that allows you to continue working, but on your terms.

Key Elements of a Work-Optional Lifestyle

1. Financial Independence: The cornerstone of a work-optional lifestyle is achieving financial independence. This means having enough savings, investments, and passive income sources to cover your living expenses, healthcare costs, and other financial needs without relying on a traditional full-time job.

2. Pursuing Passions: One of the main benefits of a work-optional lifestyle is the opportunity to pursue your passions and interests. Whether it’s starting a small business, volunteering, or exploring new hobbies, this lifestyle allows you to allocate your time to activities that bring you joy and fulfillment.

3. Flexibility: A work-optional lifestyle offers the flexibility to scale your work commitments up or down as needed. You can choose part-time work, freelance opportunities, or consulting roles that align with your interests and skills without the pressure of a traditional 9-to-5 job.

4. Health and Well-being: Retirees who embrace a work-optional lifestyle often report better mental and physical health. Staying engaged in meaningful activities and maintaining social connections can contribute to a longer, happier, and healthier retirement.

How to Achieve a Work-Optional Lifestyle

1. Financial Planning: Start by working with a financial advisor to create a comprehensive retirement plan. Assess your current financial situation, set clear retirement goals, and determine how much income you’ll need to maintain your desired lifestyle.

2. Savings and Investments: Build a diversified investment portfolio that includes stocks, bonds, real estate, and other assets. Consider tax-efficient strategies to maximize your retirement savings and minimize tax liabilities.

3. Passive Income Streams: Explore passive income sources such as rental income, dividends, interest, and annuities. These can help cover your basic expenses and reduce the need for full-time employment.

4. Debt Management: Pay off high-interest debt before retiring to reduce financial stress and free up more of your retirement income for discretionary spending.

5. Insurance and Healthcare: Ensure you have adequate health insurance coverage and consider long-term care insurance to protect against unexpected medical expenses.

6. Budgeting: Create a detailed retirement budget that includes both essential and discretionary expenses. This will help you track your spending and make informed decisions about how much you can comfortably work or reduce expenses if needed.

A work-optional lifestyle in retirement represents a paradigm shift in how we view our golden years. It’s about achieving financial independence and having the freedom to work on your terms while pursuing your passions and enjoying a fulfilling retirement. As financial advisors, our goal is to help you create a retirement plan that not only secures your financial future but also allows you to embrace this exciting and enriching way of life. If you’re interested in exploring the possibilities of a work-optional retirement, we’re here to guide you on your journey toward a more rewarding retirement experience.

https://platinumtreefinancial.ca/wp-content/uploads/2024/10/Add-a-heading.jpg 300 500 Platinum Tree Financial https://platinumtreefinancial.ca/wp-content/uploads/2020/03/platinumTreeEnfold.jpg Platinum Tree Financial2024-10-01 06:00:002024-10-01 06:00:35Embracing a Work Optional Lifestyle in Retirement

Different types of life insurance explained

September 2, 2024/in Blog, Insurance/by Platinum Tree Financial

Different types of life insurance explained

You may already have or are interested in life insurance because it can provide significant financial protection for you and your family. To get the best coverage that suits your needs and lifestyle, it is essential to be familiar with the four most common types of life insurance available:

  1. Term life insurance
  2. Permanent life insurance
  3. Participating life insurance
  4. Universal life insurance

1) Term life insurance

Term life insurance provides coverage for a specific period, such as five, ten, or even fifteen or twenty years. Once that term is up, you can choose to renew your policy – but your premiums may go up.

If you die while your term life insurance policy is in effect, your beneficiaries will receive a tax-free death benefit equal to the amount of coverage you selected. Your beneficiaries can then use that benefit to pay for whatever they choose, such as debts, a mortgage, tuition, and everyday living expenses.

2) Permanent life insurance

With permanent life insurance, you will have coverage for your whole life. In addition, the cost of insurance can be structured so that the cost does not increase as you age, even if your health worsens. However, the level cost for life means that permanent life insurance may be more expensive than term insurance premiums in the early years but potentially less costly than term insurance premiums as you age.

As with term life insurance, your beneficiaries will be entitled to a tax-free death benefit after you die. Permanent life insurance also offers a cash value feature. You can use this cash value as collateral for a loan or withdraw the value – but this will reduce your death benefit.

3) Participating life insurance

Participating life insurance is a type of permanent life insurance – which offers the added bonus of letting you earn dividends. With these earned dividends, you can either reinvest them to help reduce the cost of your premiums or withdraw them as cash.

As with all life insurance policies, upon your death, your beneficiaries will receive a tax-free death benefit to spend as they deem fit.

4) Universal life insurance

Universal life insurance is also another form of permanent life insurance. Along with a tax-free death benefit, Universal Life also lets you invest extra money (if you choose) that can grow in a tax-advantaged account! With universal life insurance, you can provide for your beneficiaries upon death while saving extra cash for yourself or your business.

We can help!

If you are unsure what kind of life insurance is best for you, give us a call today! We can answer any questions about these different kinds of life insurance and what features and benefits are best for you.

https://platinumtreefinancial.ca/wp-content/uploads/2024/09/Different-types-of.png 300 500 Platinum Tree Financial https://platinumtreefinancial.ca/wp-content/uploads/2020/03/platinumTreeEnfold.jpg Platinum Tree Financial2024-09-02 06:00:002024-09-02 06:00:29Different types of life insurance explained

What is disability insurance?

August 1, 2024/in Blog, business owners, disability, disability insurance, Family, farmers, financial advice, health benefits, incorporated professionals, individuals, Insurance, Professionals/by Platinum Tree Financial

If you cannot work because you are seriously injured or ill, disability insurance will provide you with a monthly, tax-free income to help replace your lost wages.  An injury does not have to be as blatant as a broken leg or arm – suffering from chronic pain or dealing with mental health issues can also qualify you for a disability insurance payout.  

Why do I need disability insurance?

Unfortunately, people become disabled – whether temporarily or permanently – quite often. In 2017, over 20 percent of Canadians had one or more disabilities. 

If you’re disabled, you may lose one of your most valuable assets – your ability to work and bring in a paycheck. Disability insurance can help replace that paycheck for as long as you need it to. Being able to rely on a disability insurance payout means you won’t have to dip into your savings if anything happens to you.

Disability insurance is especially important if you are self-employed, particularly if you are the family’s sole income earner.

What if I already have disability insurance through work?

If you have disability insurance through work, that’s great – but it may not replace 100 percent of your paycheck, especially if you’re off work for a long time. If you purchase private disability insurance, you can:

  • Choose how much coverage you want.
  • Adjust your coverage as needed.
  • Not have to worry if you leave your employer – you won’t lose your disability insurance coverage.

Having private disability insurance will give you peace of mind that you either have additional coverage if you are employed and at least some disability coverage if you lose your job.

How does disability insurance work?

We’d be happy to answer any questions you have about disability insurance. There are five main steps to disability insurance:

  1. Determine the amount of coverage you want. The higher your salary, the more coverage you should get.
  2. Pay your monthly premiums. Factors like your health, your age, and the amount of coverage you have will all impact the cost of your premiums.
  3. File a claim if you become disabled – we can help you with this.
  4. Receive your monthly payments once your waiting period has passed – a longer waiting period can lower your premiums, but it does mean you’ll go longer without any income.
  5. When you are healthy enough to return to work, or your coverage period runs out, you will stop receiving disability insurance payments.

We’re Here To Help

If you’d like to know more about disability insurance – from how much it would cost you to what you can file a claim for – we’re here to help! Give us a call today.

https://platinumtreefinancial.ca/wp-content/uploads/2024/08/What-is-disability-insurance.jpg 300 500 Platinum Tree Financial https://platinumtreefinancial.ca/wp-content/uploads/2020/03/platinumTreeEnfold.jpg Platinum Tree Financial2024-08-01 06:00:352024-08-01 10:49:49What is disability insurance?

Network of Professionals

June 3, 2024/in Accountants, Blog, business owners, Center of Influences, Estate Planning, Family, farmers, financial advice, Financial Planning, incorporated professionals, individuals, Insurance, Investment, life insurance/by Platinum Tree Financial

Our Network of Professionals

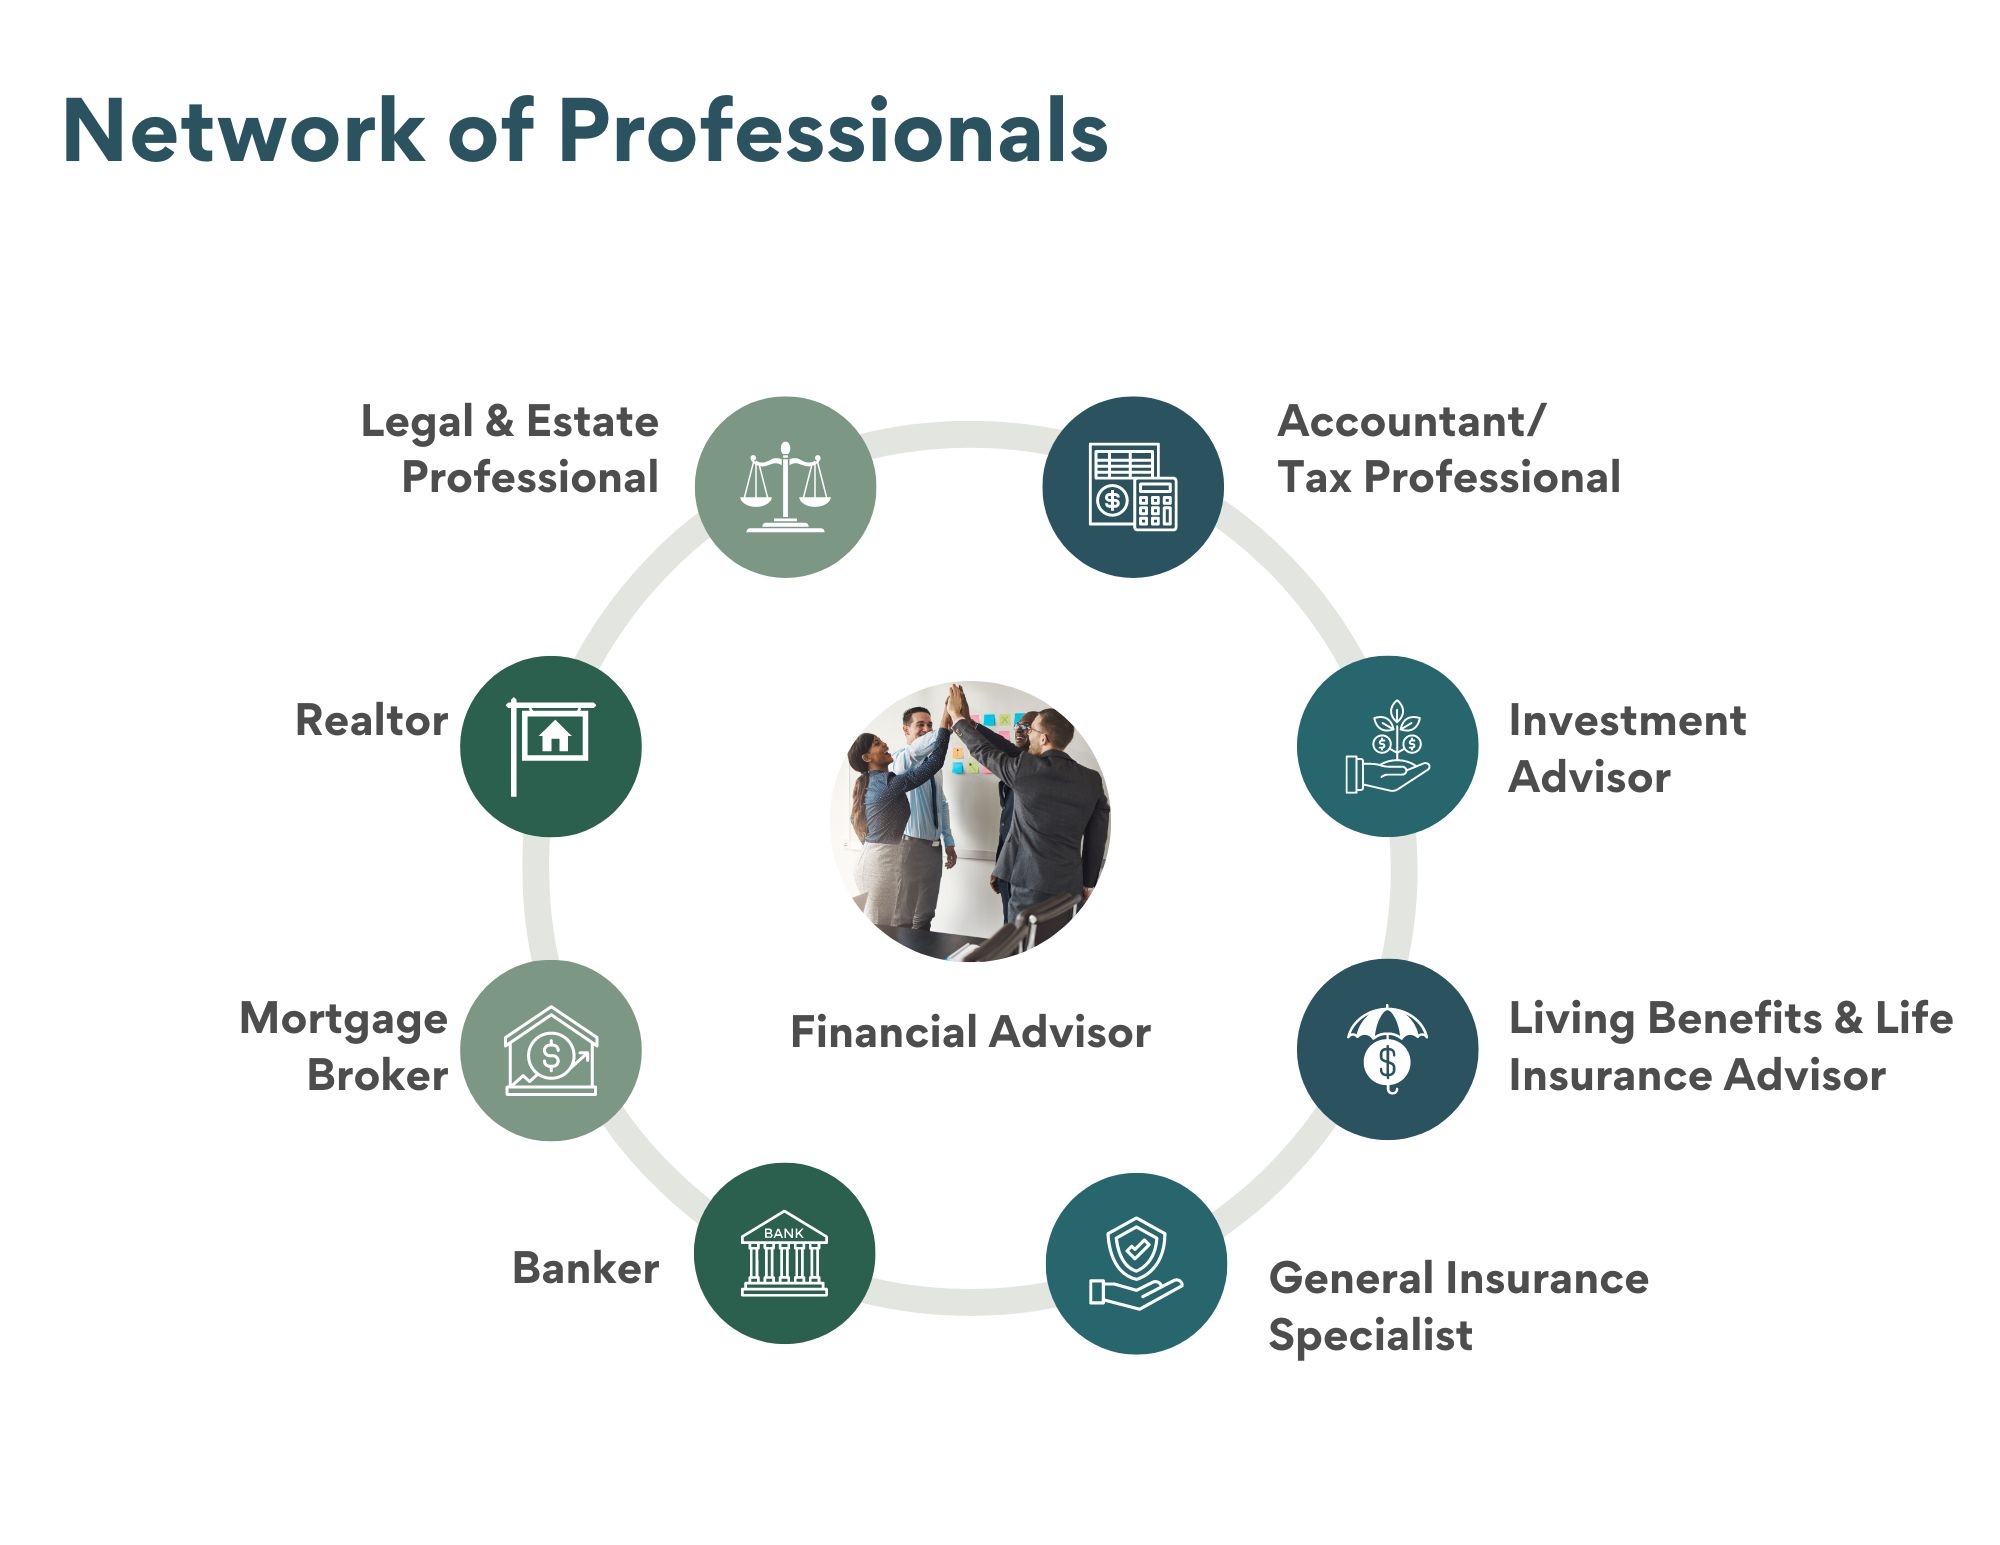
As a financial advisor, my primary goal is to help you achieve financial clarity. I do this by accessing a network of dedicated professionals, each bringing their unique expertise to the table. Together, we provide personalized advice and services that help you make informed decisions and secure your future.

Financial Advisor

Think of me as your financial coordinator. I help you figure out your goals, create plans to achieve them, and keep everything on track. Whether it’s planning for retirement, managing investments, or saving for a major purchase, I have access to a network of professionals who ensure every aspect of your financial life works together smoothly.

Accountant/Tax Professional

Having an accountant or tax professional in your financial network is essential for keeping your financial records in order. They handle tasks like bookkeeping, preparing financial statements, and assisting with tax planning. Their role is particularly important during tax season. They help you file your taxes accurately and on time, taking the stress out of the process. By optimizing your tax strategies and ensuring everything is reported correctly, they help you save money. Their skills are invaluable for both your immediate needs and long-term financial planning.

Investment Advisor

Investment advisors focus on building and managing investment portfolios tailored to your short-term, medium-term, and long-term goals. They thoroughly research the market, evaluate investment opportunities, and offer valuable insights to help you create a well-rounded portfolio. Whether you’re saving up for a major purchase, planning for retirement, or aiming for other financial milestones, they assist in choosing the right investment vehicles, such as RRSPs, TFSAs, RRIFs, and non-registered accounts, to support your financial stability and future needs.

Life Insurance and Living Benefits Advisor

Life insurance and living benefits advisors are here to help you protect your greatest asset: yourself. Their job is to make sure you and your family are financially secure if unexpected events occur. These advisors walk you through different insurance options, including disability insurance, critical illness insurance, and life insurance, to find the coverage that fits your needs best. By understanding your unique situation and recommending the right policies, they provide you with peace of mind, knowing that you have a safety net in place for life’s uncertainties.

General Insurance Specialist

General insurance specialists cover a wide range of insurance needs, including auto, property, travel, and liability insurance. They assess your risks and recommend policies that provide the protection you need. Their advice helps you understand your options, compare quotes, and select the best policies to safeguard your assets, ensuring you are well-protected in various aspects of your life.

Banker

Bankers are there to help you navigate a wide range of financial services, especially when it comes to getting loans and credit products. They offer advice on securing personal loans, understanding credit options, and managing debt effectively. Whether you’re looking to finance a major purchase, consolidate debt, or build your credit, bankers provide the support and guidance you need to make informed financial decisions.

Mortgage Broker

Mortgage brokers assist you in securing financing for property purchases by accessing multiple lenders on your behalf. They assess your financial situation, compare mortgage products from various sources, and recommend the best options for you. With their ability to shop around and understand different interest rates, loan terms, and application processes, they ensure you get the best possible mortgage deal, making homeownership more accessible and affordable.

Realtor

Realtors are your go-to professionals for buying or selling property. They provide market insights, negotiate deals, and manage the legal aspects of real estate transactions. With their knowledge of local market trends and property values, realtors help you make informed decisions whether you’re purchasing a home, investing in real estate, or selling property.

Legal & Estate Professional

Legal and estate professionals play a vital role in your financial planning by handling the legal side of things, such as estate planning, wills, trusts, and probate. They make sure your assets are distributed according to your wishes and that all the necessary legal documents are properly set up. Their guidance helps you reduce estate taxes and smoothly navigate the legal processes, ensuring your wealth is transferred to future generations just as you intended.

Having a network of financial professionals is essential for achieving financial well-being. Each member brings their own expertise to address different aspects of your finances, from investments and insurance to legal and real estate matters. As your financial advisor, I act as the coordinator, ensuring that all these professionals work together seamlessly. By leveraging their combined knowledge and skills, you can gain financial clarity and know that every aspect of your financial life is taken care of.

Ready to take control of your financial future? Contact us today.

https://platinumtreefinancial.ca/wp-content/uploads/2024/06/Network-of-Professionals-FI.png 700 1200 Platinum Tree Financial https://platinumtreefinancial.ca/wp-content/uploads/2020/03/platinumTreeEnfold.jpg Platinum Tree Financial2024-06-03 12:01:592024-06-03 12:14:40Network of Professionals

Empowering Your Family’s Financial Future: A Comprehensive Guide to Budgeting

May 1, 2024/in Blog, Debt, disability, disability insurance, Family, financial advice, Financial Planning, individuals, Insurance, rdsp/by Platinum Tree Financial

Taking charge of your family’s financial well-being through effective budgeting is a crucial step in securing a brighter future. We’ll explore the significance of budgeting and provide practical tips to help you manage your money wisely while ensuring the best possible support for your loved ones, including those with disabilities and their Registered Disability Savings Plan (RDSP).

Why Budgeting Matters for Families

Budgeting is a powerful financial tool that holds importance for all families:

  1. Financial Clarity: It offers a clear overview of your family’s income and expenses, helping you make informed decisions about allocating funds.
  2. Goal Achievement: Budgeting helps you allocate funds not only for your loved one’s RDSP but also for other family financial goals, such as saving for education or a home.
  3. Expense Control: It identifies areas where you can cut back on expenses, freeing up money for your family’s financial priorities.
  4. Debt Reduction: By tracking spending, you can allocate extra funds to pay down debt faster, ensuring your family’s financial stability.
  5. Emergency Preparedness: A budget provides a financial safety net for unexpected expenses, which can be especially critical for families with additional financial responsibilities.

Steps to Effective Budgeting for Families

  1. Calculate Income: Determine your total monthly income, including salaries, government benefits, and any disability-related support for your loved one.
  2. List Expenses: Categorize expenses into fixed (e.g., housing, utilities) and variable (e.g., groceries, entertainment).
  3. Set Financial Goals: Define short-term and long-term financial goals for your family, ensuring that your loved one’s RDSP contributions are part of the plan.
  4. Create a Budget: Use budgeting tools or apps to allocate income to expenses, savings, and financial goals without exceeding your income.
  5. Monitor and Adjust: Regularly track spending against your budget, making necessary adjustments to ensure your family’s financial health.

Tips for Successful Budgeting

  1. Be Realistic: Set achievable goals and create a budget that accommodates your family’s unique needs, including the financial responsibilities associated with the RDSP.
  2. Prioritize Savings: Ensure that contributing to your loved one’s RDSP is a top financial priority, but don’t forget to save for other family goals too.
  3. Emergency Fund: Maintain an emergency fund to cover unexpected expenses, which can benefit all family members.
  4. Review and Cut Expenses: Periodically review expenses to find areas where you can save and allocate more funds to your family’s financial priorities.
  5. Pay Yourself First: Treat savings, including RDSP contributions, as non-negotiable expenses, just like other essential bills.
  6. Seek Professional Advice: Consult a financial advisor who specializes in disability-related financial planning for tailored guidance.

Budgeting is your family’s pathway to financial security and ensuring a brighter financial future. By budgeting wisely and prioritizing your loved one’s financial well-being, you can control your family’s finances, reduce stress, and work towards a future filled with financial peace of mind. Remember, financial success for families means making informed choices that align with your values and aspirations. Start budgeting today to achieve financial wellness for your entire family, balancing the needs of all family members, including those who rely on the support of the RDSP.

https://platinumtreefinancial.ca/wp-content/uploads/2024/05/Add-a-heading.jpg 300 500 Platinum Tree Financial https://platinumtreefinancial.ca/wp-content/uploads/2020/03/platinumTreeEnfold.jpg Platinum Tree Financial2024-05-01 06:00:002024-05-01 06:02:01Empowering Your Family’s Financial Future: A Comprehensive Guide to Budgeting

Protecting Key Talent using Group Benefits

October 2, 2023/in 2023, Blog, business owners, corporate, dental benefits, disability, Group Benefits, health benefits, Insurance, life insurance, pension plan, Professional Corporations, Professionals, retirement/by Platinum Tree Financial

Building a Sustainable Future Together

As a group benefits specialist, our main objective is to foster a sustainable future by working in partnership with our clients. We believe that a knowledgeable and engaged workforce is essential for any organization’s success. One of the crucial aspects of achieving this goal is protecting key talent within your company. In this article, we will explore how group benefits can play a significant role in safeguarding your organization’s most valuable asset: its people.

The Value of Key Talent

Key talent refers to those employees who possess critical skills, expertise, and knowledge that drive your company’s growth and success. They are the backbone of your organization, ensuring it thrives in today’s competitive landscape. Retaining these valuable individuals is vital as their loss can have a significant impact on your business operations, productivity, and overall morale.

Challenges in Retaining Key Talent

In today’s dynamic job market, retaining key talent can be challenging. Many factors come into play, such as attractive offers from competitors, personal growth opportunities, work-life balance, and employee well-being. As an employer, understanding and addressing these challenges are essential to protect your top performers and maintain a competitive edge.

The Role of Group Benefits

Group benefits can be a powerful tool in attracting and retaining key talent. By offering comprehensive and customized benefits packages, you demonstrate your commitment to your employees’ well-being, security, and future. Here are some key aspects of group benefits that contribute to protecting your key talent:

1. Health and Wellness Coverage

Providing robust health and wellness benefits, including medical, dental, and vision coverage, not only promotes a healthy workforce but also demonstrates your dedication to their overall well-being. When employees feel supported in their health, they are more likely to remain loyal to your organization.

2. Income Protection

Group benefits often include disability insurance, which provides financial protection for employees who might experience an injury or illness that prevents them from working. This security helps ease financial worries during challenging times and creates a sense of stability, encouraging key talent to stay with your company for the long term.

3. Retirement Planning

A well-designed retirement plan is an attractive feature for key talent. It shows that you care about their future and are committed to helping them achieve financial security during their retirement years. Contributing to a retirement plan also reinforces a collaborative and client-focused relationship with your employees.

4. Work-Life Balance Support

Offering benefits that support work-life balance, such as flexible work arrangements, paid time off, and family leave, shows your understanding of the importance of a balanced life. Employees who feel they have the flexibility to manage their personal and professional responsibilities are more likely to stay committed to your organization.

5. Career Development

Group benefits can extend beyond traditional offerings. Consider including professional development and training opportunities within your benefits package. Investing in your employees’ growth not only enhances their skills but also reinforces your commitment to their long-term success.

Educational Approach and Collaboration

Our mission as group benefits specialists is to provide educational and collaborative support to our clients. By engaging in open discussions about your organization’s needs and goals, we can tailor group benefits packages that align with your unique requirements. Together, we can build a sustainable future by nurturing and protecting your key talent.

Protecting key talent using group benefits is not just a sound business strategy; it reflects a client-focused, educational, and collaborative approach to employee welfare. As a group benefits specialist, we are committed to working hand-in-hand with our clients to create comprehensive and customized solutions that safeguard their organization’s most valuable asset – their people. By investing in the well-being, security, and future of your employees, you are not only enhancing loyalty and retention but also building a stronger and more sustainable future for your company. Let’s continue to partner together to ensure a prosperous and thriving workforce.

https://platinumtreefinancial.ca/wp-content/uploads/2023/10/Protecting-Key-Talent.jpg 350 500 Platinum Tree Financial https://platinumtreefinancial.ca/wp-content/uploads/2020/03/platinumTreeEnfold.jpg Platinum Tree Financial2023-10-02 06:00:002023-10-02 06:04:54Protecting Key Talent using Group Benefits
Page 1 of 212

Book a Meeting

Search Blog Posts

Search Search

Latest News

  • What Happens to Your Group Benefits When You Leave a Job?October 1, 2026 - 9:03 am
  • Empowering Your Family’s Financial Future: A Comprehensive Guide to BudgetingSeptember 1, 2026 - 11:25 am
  • You Just Inherited Money: What to Do FirstAugust 3, 2026 - 1:07 pm

Categories

  • 2020
  • 2020 Only
  • 2021
  • 2022
  • 2022 Only
  • 2023
  • 2024
  • 2025
  • 2026
  • Accountants
  • Blog
  • Business Owners
  • business owners
  • buy sell
  • Center of Influences
  • Charitable Gifting
  • Coronavirus
  • Coronavirus – Associates
  • Coronavirus – Practice Owners
  • Coronavirus – Retired
  • Coronavirus – Retiring
  • Coronavirus – Students
  • corporate
  • critical illness insurance
  • Debt
  • dental benefits
  • disability
  • disability insurance
  • Estate Planning
  • Families
  • Family
  • farmers
  • financial advice
  • Financial Planning
  • Government Budget
  • Group Benefits
  • health benefits
  • incorporated professionals
  • individuals
  • Insurance
  • Investment
  • life insurance
  • long term care
  • mortgage
  • pension plan
  • personal finances
  • Professional Corporations
  • Professionals
  • rdsp
  • Registered Education Savings Plan
  • Retirees
  • retirement
  • rrsp
  • tax
  • Tax Free Savings Account
  • travel insurance

Adrian Belcourt

Financial Advisor
T: (780) 850-8020
E: Adrian@platinumtreefinancial.ca

About

Educate, Empower, Enjoy

Latest News

  • What Happens to Your Group Benefits When You Leave a Job?October 1, 2026 - 9:03 am
  • Empowering Your Family’s Financial Future: A Comprehensive Guide to BudgetingSeptember 1, 2026 - 11:25 am
  • You Just Inherited Money: What to Do FirstAugust 3, 2026 - 1:07 pm
©2020 Financial Tech Tools Inc. | Privacy Statement and Terms of Use
  • Link to LinkedIn
  • Link to Facebook
  • Link to LinkedIn
  • Link to LinkedIn
Scroll to top Scroll to top Scroll to top